Market Overview
Prepared: 31 October 2026 · Currency: USD for market size, SAR for retail prices
Bottom line. Three independent research houses put the 2025 Saudi sports-nutrition market at USD 389 million, USD 545 million and USD 610 million — a 57% spread that reflects different definitions and channel coverage, not a data error. All three agree on 8–11% annual growth. Sports drinks are the largest single segment (~41% per Grand View), so the addressable non-drinks market is roughly USD 230–362 million, with a planning midpoint of ~USD 323 million. That is small in absolute terms but under-penetrated: about USD 8.7 per capita per year for non-drink sports nutrition, against a young, 73% working-age population and a gym chain that alone claims 400,000+ members. The opportunity is real but narrow: whey, creatine and mass gainers are the volume pools; pre-workout is the margin pool; weight management is the biggest pool but the most claims-sensitive.
1. Market size: three estimates and a reconciliation
| Source | Published | 2025 size | Forecast | CAGR | Scope | Reliability |
|---|---|---|---|---|---|---|
| Ken Research, Saudi Arabia Sports Nutrition and Supplements Market, Aug 2026 [S16] | Aug 2026 | USD 545 m | USD 934 m by 2032 | 8.0% (2025–32) | Sports nutrition + supplements; includes sports drinks; 27.2 m packs; ASP USD 20.04 | Medium-high (paid report, transparent methodology summary) |
| Grand View Research Horizon, Saudi Arabia sports nutrition, 2025 [S15] | 2025 | USD 388.7 m | USD 716.6 m by 2033 | 8.0% (2026–33) | Sports nutrition incl. sports drinks, supplements, meal replacement, sports foods, weight loss | Medium-high (global publisher, free summary) |
| IMARC, Saudi Arabia Sports Nutrition Market, last updated 19 Nov 2025 [S14] | 19 Nov 2025 | USD 610.4 m | USD 1,612.7 m by 2034 | 11.4% (2026–34) | Sports nutrition by product (drinks, food, supplements), raw material, channel, region | Medium (publisher summary; methodology not public) |
Reconciliation. The three estimates differ because:
- Category boundaries. Grand View separates "sports nutrition" from "weight loss" and "meal replacement" in its taxonomy but includes them in the headline; IMARC includes sports drinks, sports food and supplements; Ken includes supplements and drinks. None is supplement-only.
- Channel coverage. Ken explicitly models online at 35% of 2025 sales and 27.2 million packs; IMARC and Grand View do not publish their channel weights in the free summaries.
- Price basis. Ken's ASP of USD 20.04 per standardised pack implies a retail-value model; the others may use manufacturer or retail value.
- Timing. IMARC's 11.4% is a 2026–34 forecast; the others use 8.0%. A 3.4-point gap compounded over nine years explains most of the 2034 difference.
Do not average them. Use the median USD 545 m as the planning anchor, and carry the full range as a sensitivity band.
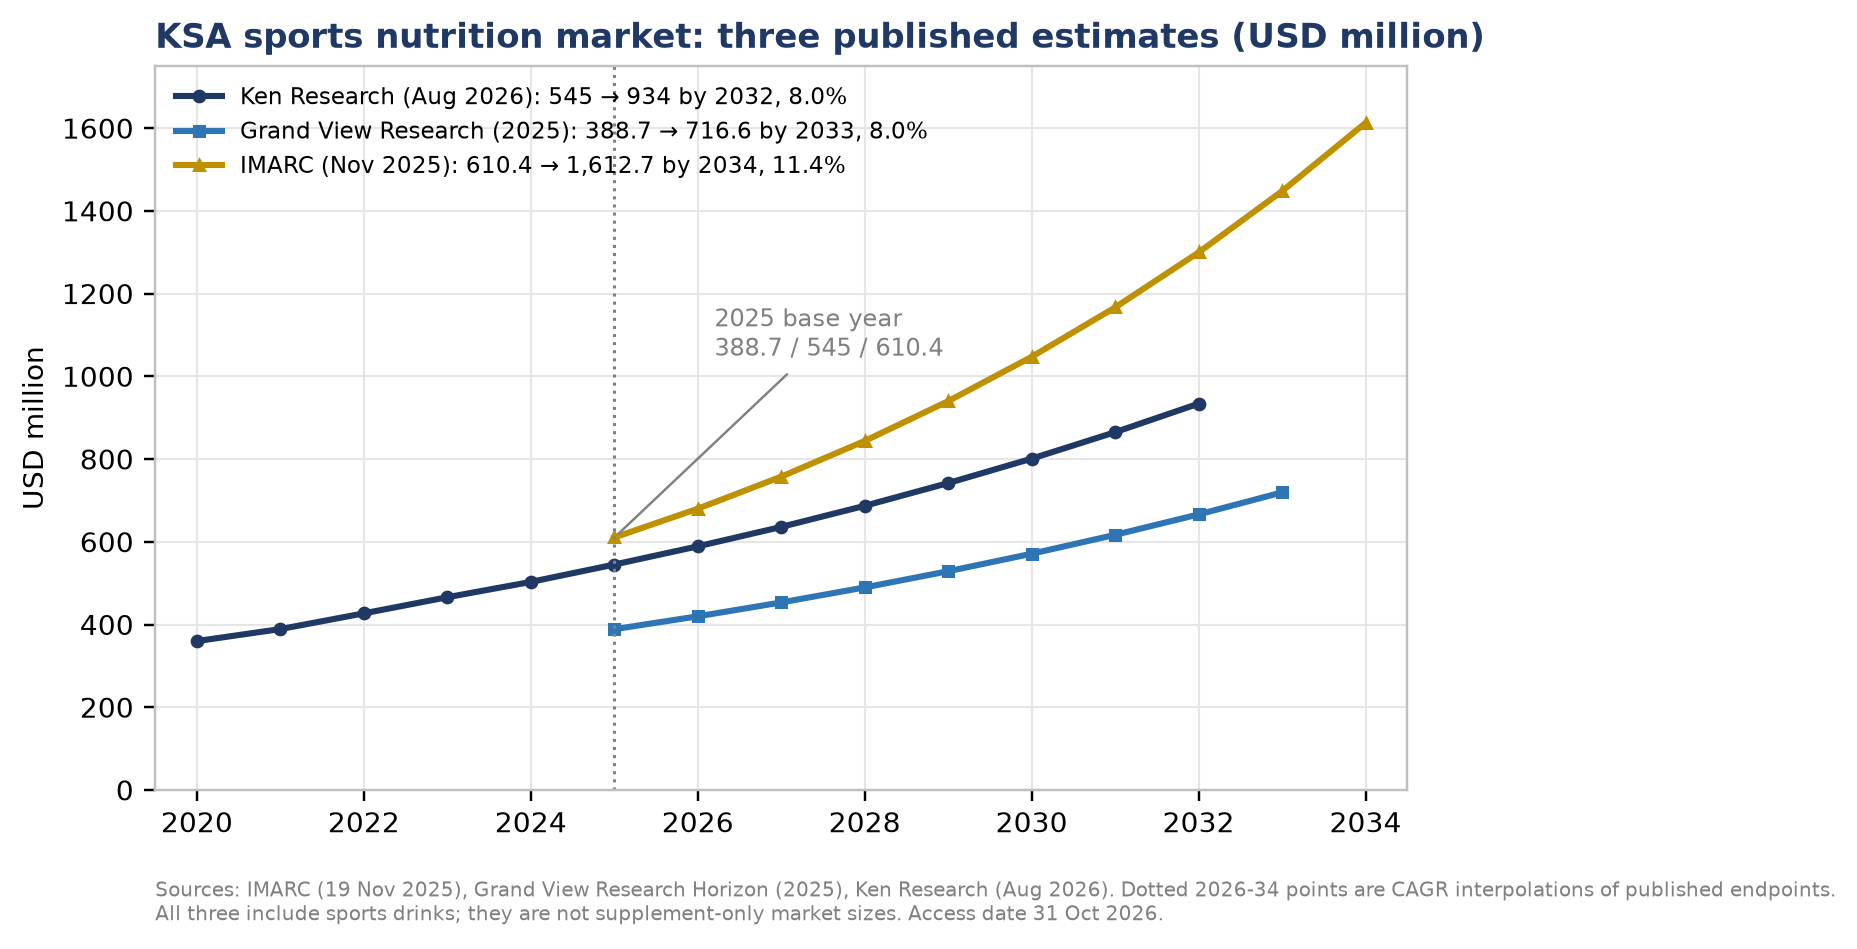
Figure 1. Three published estimates, 2020–2034. Dotted points are CAGR interpolations of published endpoints. All three include sports drinks.
Derived non-drinks market (ESTIMATE)
Grand View publishes that sports drinks were 40.7% of 2025 revenue [S15]. Applying that share to each total:
| Source | Total 2025 (USD m) | Sports drinks @ 40.7% | Non-drinks (supplements, foods, meal replacement, weight management) |
|---|---|---|---|
| Grand View | 388.7 | 158.2 | 230.5 |
| Ken Research | 545.0 | 221.8 | 323.2 |
| IMARC | 610.4 | 248.4 | 362.0 |
| Planning midpoint | 545.0 | 221.8 | 323.2 |
This is a derived estimate, not a published supplement-only figure. It assumes Grand View's segment mix applies to all three totals, which may not hold. Treat the non-drinks number as a range of USD 230–362 m, with ~USD 323 m for planning.
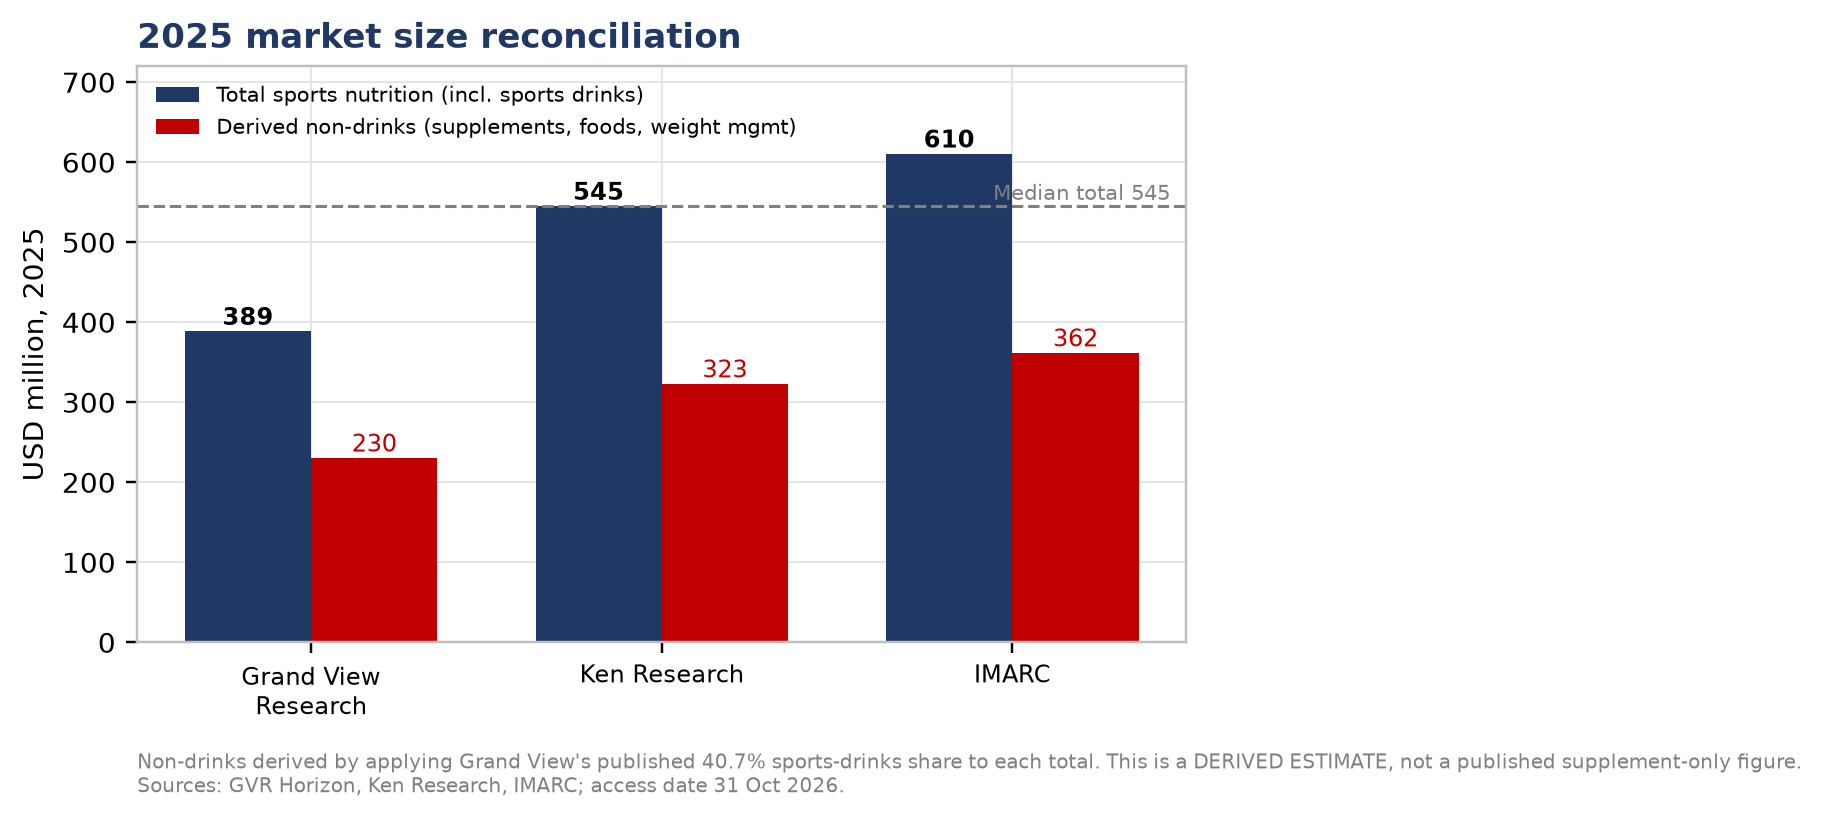
Figure 2. Reconciliation of the 2025 totals and the derived non-drinks segment. The non-drinks bars are an estimate, not a published figure.
Per-capita sanity check
- Population, 2025: 36.97 million (World Bank) [S17].
- Total sports nutrition per capita: 545 ÷ 36.97 = USD 14.7/year.
- Non-drinks per capita: 323.2 ÷ 36.97 = USD 8.7/year.
No directly comparable per-capita benchmark was sourced in this study. The absolute spend is low for a high-income market, which is consistent with under-penetration; it is also a warning that mass-market penetration is still thin.
Volume and price
Ken Research models 27.2 million standardised retail packs in 2025, rising to 42.8 million by 2032 (6.7% volume CAGR), with average retail value per pack rising from USD 20.04 to USD 21.82 [S16]. That implies roughly two-thirds of value growth is volume-led, one-third price/mix. For a new brand, that is favourable: growth does not depend on premiumisation alone.
2. Growth drivers
2.1 Vision 2030 and sport participation
- GASTAT's 2022 household survey found 48.2% of people practice sport for at least 30 minutes a week; 54.8% of males and 38.3% of females [S19]. The most active regions were Eastern Province, Riyadh and Asir.
- The 2019 GASTAT survey used a stricter 150-minutes-per-week definition and is the baseline for the Vision 2030 target of raising weekly sport participation to 40% [S18][S15]. The two definitions are not comparable; cite the 48.2% (any weekly activity) and the 150-minute metric separately.
- The Quality of Life programme and the Saudi Sports for All Federation have launched dozens of community programmes; the 2025 Riyadh Marathon drew 40,000+ participants, 40% women (Ken Research) [S16]. These are demand-creation events, not just marketing.
2.2 Demographics
- 73.3% of the population is 15–64; 23.6% is under 15 (World Bank, 2025) [S17].
- A young, working-age population with disposable income is the core gym and supplement demographic.
- The expatriate population (Ken Research: ~15.7 m non-Saudis in 2024) is a second demand pool with brand awareness of international labels [S16].
2.3 Gym and fitness infrastructure
- Leejam (Fitness Time) reports 178+ gyms, 400,000+ members, 13 brands and 650+ sports facilities on its corporate site [S20]. Leejam describes itself as the largest gym chain in MENA. This is a concentrated, addressable sampling and retail channel.
- Boutique studios, CrossFit boxes, padel clubs and women-only gyms are expanding; they are harder to measure but matter for premium isolates and pre-workout.
- The Saudi Sports Law entered into force in June 2026 and club privatisation is underway (Ken Research) [S16]; this professionalises sponsorship and athlete partnerships.
2.4 Obesity, diabetes and weight management
SFDA's 2025 healthy-food regulations explicitly aim to reduce chronic disease rates [S7], and weight management is a core demand pool. This study did not source a KSA obesity/diabetes prevalence figure; treat the driver as directional, not quantified. It drives demand for meal replacements and protein-led weight management, and it drives regulatory scrutiny of slimming claims: the claims regime is restrictive and weight-loss products are an enforcement priority.
2.5 E-commerce and digital payments
- E-commerce is ~10% of total retail and is forecast to exceed 25% by 2035 (McKinsey, cited by ITA, May 2026) [S12].
- 34.5 million e-commerce users by end-2025; Amazon.sa is the largest international marketplace, alongside Noon, Jarir, Jahez and Salla [S12].
- 85% of retail payments were electronic in 2025 (Ken Research) [S16].
- For NBP, this means a lean launch is possible without a national retail footprint: Amazon.sa + Instagram + a 3PL can reach Riyadh, Jeddah and Dammam in weeks.
2.6 Social-media fitness culture
Fitness content is among the highest-engagement categories on TikTok, Instagram and Snapchat in KSA. It lowers customer-acquisition cost for brands with credible creators, but it also amplifies claims risk: an influencer saying "fat burner" is an advertisement under Saudi rules. NBP has no Arabic content or local ambassadors today.
3. Segmentation: where the money is
No public source gives a clean SAR split by product segment for KSA. The table combines the published category structure with Amazon.sa price/velocity signals and the NBP portfolio. Shares are qualitative; do not quote them as market facts.
| Segment | Evidence of size/direction | Price points in KSA (Amazon.sa, 31 Oct 2026) | NBP fit |
|---|---|---|---|
| Sports drinks / hydration | 40.7% of 2025 sports nutrition (GVR) [S15]; Gatorade/Powerade/Bodyarmor dominate | Not applicable to NBP | None (no RTD) |
| Whey / protein | Largest non-drink pool; highest repeat purchase; ON 2 lb has 63.3K ratings, 5 lb 482; Dymatize ISO100 8.9K on 20-serving | 5 lb: SAR 338–796; isolate premium SAR 554–796 | Core — ProWhey, ISO-Whey, Extreme ISO |
| Mass gainers | Niche but high ticket; strong gym culture; ON Serious Mass 6 lb SAR 222; Mutant 5 lb SAR 629 | 5–6 lb: SAR 145–629; 10–13 lb: SAR 334–419 | Strong — Extreme Mass |
| Creatine | Commodity, evidence-led, growing; 400 g SAR 104–129; 500 g SAR 105–169 | SAR 69–169 per 300–500 g | Strong — Creatine 400 g |
| Pre-workout | High velocity, high margin; ABE 30 srv SAR 94–140; Ghost SAR 201; C4 SAR 129 | SAR 94–212 per 30 servings | Conditional — Pre-Workout (reformulate/relabel) |
| BCAA / amino | Softening globally; capsule formats underdosed; ON BCAA 200 caps SAR 153 | SAR 69–164 per 60–240 caps | Weak — BCAA 1.2 g/day |
| Fat burners / weight management | Large but claims-sensitive; Herbalife dominates direct sales; garcinia 60 caps SAR 138 | SAR 127–199 | High risk — Lipofel |
| Meal replacement / meal complement | Herbalife 500 g SAR 130–135; Garden of Life 475–509 g SAR 193–199; Quest 726 g SAR 203 | SAR 130–369 | Moderate — TrimFit (reposition) |
| Vitamins / general wellness | Adjacent, not NBP's range | — | None |
Two implications:
- Whey and creatine are the only segments where NBP can win on value without a claims fight. Its price per gram of protein is at or below ON (Section 04), and creatine is a commodity where a correct 5 g dose and a clean label are enough.
- Mass gainers are a Saudi-specific opportunity. The category is less crowded than whey, the ticket is high, and the "hard gainer" narrative resonates in gym culture. But NBP's 375 g/1,582 kcal serving and 60 g sugar are a formulation liability.
4. Seasonality
| Period | Behaviour | Implication |
|---|---|---|
| Ramadan (moving; ~Feb–Mar 2027) | Training shifts to late night; caffeine/pre-workout consumption falls during fasting; weight-management and meal-replacement demand rises; gifting increases | Promote protein/meal replacement, not stimulants; adjust delivery windows |
| Eid al-Fitr / Eid al-Adha | Gifting, travel, gym closures | Bundle offers; pause auto-replenishment |
| Summer (Jun–Sep) | Travel, indoor gyms, heat; warehouse temperatures high | Air-conditioned storage; avoid sea shipments arriving in peak heat; hydration messaging |
| Riyadh Season (Oct–Mar) | Events, fitness activations, tourism, higher footfall | Sampling, influencer events, sponsorship |
| Back-to-school / new year | Resolution-driven gym sign-ups | Creatine/whey bundles, 12-week challenge |
| Hajj | Pilgrim traffic; retail disruption in Makkah/Jeddah; SFDA inspection campaigns | Avoid launch in Hajj week; ensure warehouse compliance |
Seasonality is qualitative; no KSA monthly sell-through data was available. The financial model does not seasonally adjust.
5. Consumer segments and personas
Price points are from Amazon.sa listings on 31 Oct 2026 [S13]; "where they buy" is based on channel structure (Section 03), not a survey.
| Persona | Who | Goals | Where they buy | What they pay (SAR) | NBP SKU |
|---|---|---|---|---|---|
| The strength trainee | Male 18–30, 3–5 gym sessions/week, often in a commercial gym | Muscle, strength, visible size | Amazon.sa, gym shops, Instagram sellers | Whey 5 lb 300–450; creatine 100–130; pre-workout 100–160 | ProWhey, Creatine, Pre-Workout, Extreme Mass |
| The competitive athlete | 18–35, sport-specific training, coach/trainer influence | Performance, recovery, trusted/third-party tested | Specialty stores, pharmacy, team/coach | Isolate 5 lb 450–800; creatine 120–170 | Extreme ISO (if certified), Creatine |
| The weight-management woman | 25–40, gym + diet, Instagram-driven | Fat loss, toning, meal replacement | Instagram, pharmacies, Amazon.sa, Herbalife distributors | Meal replacement 130–200; slimming 100–190; carnitine 100–130 | TrimFit, L-Carnitine, Lipofel (claims risk) |
| The general wellness user | 35–55, walks/light gym, doctor/pharmacist advice | Energy, bone/muscle maintenance, "healthy ageing" | Pharmacies, hypermarkets | Protein 200–350; vitamins 50–150 | ProWhey (small pack), TrimFit |
| The expat / value buyer | 25–45, price-sensitive, brand-aware | Bulk protein at low cost per gram | Amazon.sa, discounters, gym shops | Whey 5 lb 250–380; mass gainer 180–250 | ProWhey, Extreme Mass 10 lb |
What this means for NBP. The brand has no awareness, no Arabic content and no local ambassadors. Its first 1,000 customers will be value-seeking strength trainees and expats who compare price per gram of protein on Amazon. The premium athlete and weight-management personas require trust signals NBP does not yet have (third-party testing, halal, Arabic label, local reviews).
6. Demand signals observed
| Signal | Observation | Source | Confidence |
|---|---|---|---|
| Amazon review depth | ON Gold Standard 2 lb: 63.3K ratings; Dymatize ISO100 20-serving: 8.9K; ON 5 lb: 482; BSN Syntha-6 5 lb: 4.7★ | Amazon.sa, 31 Oct 2026 [S13] | High |
| "Bought in past month" badges | ON 2 lb: 500+; ON 5 lb: 300+; Dymatize 20 srv: 100+ | Amazon.sa [S13] | High |
| Gym scale | Leejam: 178+ gyms, 400K+ members | Leejam corporate site [S20] | High (company-reported) |
| Sport participation | 48.2% weekly (30+ min); 54.8% male / 38.3% female | GASTAT via Arab News, Jul 2022 [S19] | Medium-high |
| E-commerce | 10% of retail → >25% by 2035; 34.5M users | ITA/McKinsey, May 2026 [S12] | Medium-high |
| Online share of category | 35% in 2025, ~49% by 2032 | Ken Research [S16] | Medium |
| NBP brand search | No NBP/NbP listings on Amazon.sa or Amazon.ae; no SFDA food registration | Amazon.sa/ae; SFDA database [S8][S13] | High (absence of evidence) |
| Google Trends | Not collected. Google blocked automated access; no Trends API was available. | Attempted 31 Oct 2026 | Gap |
What is missing. No sell-through data by SKU, no Google Trends index, no Noon/Nahdi shelf data, no consumer survey. The demand case rests on category growth, gym scale, marketplace review depth and the absence of the brand (white space), not on observed NBP demand.
7. Market size conclusion
- Planning anchor: USD 545 m total sports nutrition in 2025; ~USD 323 m non-drinks (derived; range 230–362).
- Growth: 8.0% (Ken, GVR) to 11.4% (IMARC). Use 8% for the base case and 11% for the optimistic case.
- Per capita: ~USD 8/year non-drinks — low, consistent with an under-penetrated, youth-heavy market.
- Where to play: whey (volume), creatine (commodity), mass gainers (ticket), pre-workout (margin, conditional). Avoid BCAA and slimming as launch pillars.
- What would change the view: a Noon/Nahdi listing data set showing protein category velocity; Google Trends showing rising Arabic search; a signed gym-chain agreement; or a competitor exiting.
Key sources for this chapter
[S8] SFDA registered food products database — https://www.sfda.gov.sa/ar/products [S12] U.S. ITA, Saudi Arabia — eCommerce, last published 19 May 2026 — https://www.trade.gov/country-commercial-guides/saudi-arabia-ecommerce [S13] Amazon.sa product listings, accessed 31 Oct 2026 — https://www.amazon.sa/ [S14] IMARC, Saudi Arabia Sports Nutrition Market, updated 19 Nov 2025 — https://www.imarcgroup.com/saudi-arabia-sports-nutrition-market [S15] Grand View Research Horizon, Saudi Arabia Sports Nutrition Market — https://www.grandviewresearch.com/horizon/outlook/sports-nutrition-market/saudi-arabia [S16] Ken Research, Saudi Arabia Sports Nutrition and Supplements Market, Aug 2026 — https://www.kenresearch.com/industry-reports/saudi-arabia-sports-nutrition-and-supplements-market [S17] World Bank, population indicators for Saudi Arabia, 2025 — https://api.worldbank.org/v2/country/SA/indicator/SP.POP.TOTL [S18] GASTAT, Household Sports Practice Survey Bulletin 2019 — https://www.stats.gov.sa/documents/20117/2435259/nshr_msh_mmrs_lsr_llryd_2019m-english.pdf [S19] Arab News, New study shows increase in physical activity across Saudi Arabia, 24 Jul 2022 — https://www.arabnews.com/sport/news/2128576 [S20] Leejam Sports Company — https://leejam.com.sa/
Full source register and reliability ratings in 07_Sources_and_Methodology.md.